Blog

The Bond Market Just Called the Administration’s Bluff

Wednesday morning, the Treasury market stopped cooperating. Yields from the 2-year through the 10-year jumped between 12 and 14 basis points before lunch. The 7-year pushed past 5 percent. The 10-year touched 5.10 percent. The trigger was S&P Global’s flash PMI, which showed an economy running hot with inflation baked into both services and manufacturing. Treasury also announced another buyback auction for Thursday. The market ignored it.

The 10-year is the number that matters most to anyone downstream of a mortgage. It rose 13 basis points to 5.10 percent, a level not seen since 2007. For two weeks it had pressed against 5 percent and fallen back. This morning it went through. The last time the benchmark sat this high, the subprime collapse was already underway. Foreclosure field services was about to become the biggest growth industry in the country.

What the data said

S&P Global’s services PMI climbed to 58.7 in September, its highest reading in nearly five years. Manufacturing hit 56.7, a level not seen in more than four years. The composite reached 58.4, and input costs rose at the fastest pace in nearly four years. Rising input costs carry the real warning. Businesses are paying more, and they will pass those costs on.

The afternoon brought worse news. A 5-year note auction cleared at 5.033 percent, far above the recent average of 4.186 percent. Indirect bidders, a group that includes foreign central banks, took only 54 percent against a typical 65 percent. Global buyers of U.S. debt were offered higher yields and still stayed home.

The administration’s tools are not working

Treasury Secretary Scott Bessent’s answer was another buyback. Treasury said it would repurchase up to $6 billion at face value in 20- and 30-year bonds. That matches the cap on the September 11 buyback, after which yields climbed further. Analysts told CNN the buybacks are too small to matter in a Treasury market worth more than $30 trillion. Six billion dollars is a gesture. The bond market recognized it as one.

The pressure is not coming only from the data. Brent crude pushed back toward $100 a barrel after Trump voiced support for a U.S. diesel export ban, feeding the inflation fears. Brent settled up 3.86 percent at $103.08. Bloomberg measured the 10-year’s intraday move as the biggest since the April 2025 “Liberation Day” tariffs. That comparison should alarm the White House. The last time the bond market moved this hard, it was reacting to this administration’s own policy.

The Federal Reserve is not offering relief either. The Fed raised rates by 25 basis points last week and signaled more hikes are coming. Governor Michael Barr suggested further hikes may be needed, and CME FedWatch put the odds of an October hike at 64 percent. Markets are not pricing a soft landing. They are pricing an administration that talks about lower rates while its tariff, energy and borrowing decisions push rates higher.

Where the bill lands

The consequences run straight downhill to Labor. Thirty-year fixed mortgage rates climbed to 7.12 percent on the same day. Higher borrowing costs strain adjustable-rate borrowers, HELOC holders and second-lien homeowners first. That strain eventually becomes delinquency. Delinquency becomes work orders for Field Service Technicians and Inspectors.

More work orders do not mean better pay. Inspections still pay $7 to $9. Grass cuts still pay $25 to $30. Winterizations still pay $45 to $50. None of those rates move when the 10-year moves. The margin expands at the order mill and the servicer. It does not expand at the truck.

Fuel runs the other direction, and it is running at a record. AAA puts today’s national diesel average at $6.52 a gallon. The all-time high was set yesterday at $6.53. A year ago, diesel averaged $3.69. The price has nearly doubled in twelve months.

Diesel is the fuel of the trailer hauls, the debris runs and the trucks that move a crew between properties. The war with Iran has disrupted the world’s flow of fuel. The President blamed Ukrainian strikes on Russian refineries for the record, even as he floats the export ban that spooked oil markets this week. Field Service Technicians and Inspectors buy their own fuel. No national has announced a fuel adjustment. None is likely to.

The tariff tax on the truck bed

Fuel is only half of what Labor pays out of pocket. The other half is materials, and the administration has taxed nearly all of them. Items made entirely or mostly from steel, aluminum or copper carry a 50 percent tariff. Derivative metal products carry 25 percent. Softwood lumber carries 10 percent, and derivative wood products carry 25 percent.

That list reads like a preservation crew’s supply run. The plywood that boards a broken window is lumber. The hasps, padlocks, hinges and screws that secure a door are steel. The copper that patches a line before a winterization is copper. Kitchen cabinets and bathroom vanities picked up their own tariffs too, with scheduled increases to 30 and 50 percent that took effect January 1. Those are the replacement parts for the work that follows a vandalized REO.

Contractors across the building trades have already felt the result. An AGC-NCCER survey found 43 percent of general contractors had a project canceled, postponed or scaled back because of tariff-driven material costs. General contractors can write escalation clauses into their bids. Field Service Technicians and Inspectors cannot. The price grid a national hands Labor has no tariff line. A preservation bid approved at last year’s pricing gets built with this year’s plywood and this year’s steel. Labor eats the difference.

This is the policy stack the bond market priced Wednesday. Tariffs raise material costs. War and export-ban talk raise fuel costs. Both feed the inflation data that pushed yields to their highest level since 2007. For Labor, each of those costs arrives as a line item on a job that pays the same as it did before any of them.

Credit gets expensive at the top

Order mills that operate on float and lines of credit now pay more to borrow. Foreclosurepedia has already documented what happens when money gets tight at the top of the chain. At NMFS and 24 Asset Management, both flagged NON-PAY in our Firm Registry, the pattern was identical. Insiders and operating bills got paid first. Labor got paid last, or never. A rate environment built for more hikes is an environment built for more of that.

The Fed’s rate hikes are also designed to cool hiring. Factory hiring in September rose at the fastest pace since February 2021. The Fed means to slow that. When the labor market softens, W-2 workers have unemployment insurance. Most Field Service Technicians and Inspectors are paid on 1099s. They have nothing.

The bottom line

The bond market delivered a verdict Wednesday. It does not believe the administration’s buybacks, its energy improvisation or its promises of cheaper money. Wall Street will hedge that risk. The servicers will pass it along. Labor will absorb it at $8 an inspection, with a tank of diesel that has never cost more.

Six Federal Filings Six Years The Same False Statement Signed by Eric Miller Every Time

A trade association whose own sitting president is embroiled in the same non-payment litigation crippling the Labor force it claims to represent. A three-year accounting-fee spike that briefly exceeded the entire membership’s dues. A legal name change filed mid-scandal. A board that, by its own admission, never sees the document before it goes to the IRS. And at the center of all of it, a federal tax filing — signed under penalty of perjury, transmitted electronically — that has named the wrong president for six straight years.

Every Form 990 carries the same declaration above the signature line: “Under penalties of perjury, I declare that I have examined this return, including accompanying schedules and statements, and to the best of my knowledge and belief, it is true, correct, and complete.” That declaration has been signed, year after year, on a document transmitted electronically to the IRS — confirmed directly by the “efile” designation ProPublica’s Nonprofit Explorer attaches to each filing, not an assumption.

For years, it was signed correctly. Then it wasn’t.

The President Who Isn’t

Treasurer Paul Magaha signed NAMFS‘s returns through at least FY2018, and while he did, the officer table tracked reality. The FY2016 return correctly lists Adam Miles as President. The FY2017 and FY2018 returns correctly list Justis Smith as President, following her actual succession to the role.

Then, starting with the FY2019 return — the first signed not by Magaha but by Executive Director Eric Miller — the roster stopped moving. Every filing since, through FY2025, lists Justis Smith as President, 8 hours a week, $0 compensation. Six consecutive years, under one man’s signature, while the actual presidency changed hands twice.

Archived snapshots of namfs.org’s own leadership page, captured independently by the Internet Archive’s Wayback Machine, show what should have replaced her:

  • July 21, 2019: Justis Smith, President, 2017–2019.
  • September 20, 2019: Matt Zoldowski, President, 2019–2021.
  • April 1, 2023: Matt Zoldowski, President, 2022–2024.
  • March 23, 2025: Chad Rulo, President, 2024–2026.

NAMFS’s own October 2022 newsletter corroborates the middle of that timeline directly: “The Officers for the 2022-24 term are: Matt Zoldowski – President.” This publication’s own reporting called Zoldowski “NAMFS President” in October 2023, and called Rulo “the latest NAMFS President” by April 2025 — independent, real-time confirmation the website’s timeline was accurate the whole time.

Treating FY2019 as the genuine transition year, six tax years — FY2020 through FY2025, all signed by Miller — are unambiguously wrong. At the 8 hours a week the return itself claims: 8 × 52 × 6 = 2,496 hours of board service attributed to a woman who left the role in 2019, on a federal document sworn true under penalty of perjury, signed by the same man, every single year, without correction.

Meanwhile, the Real President Is in Court

The man NAMFS’s own website says actually holds the presidency is not a bystander to this industry’s worst pattern. Chad Rulo is CEO of First Rate Field Services — and, per this publication’s own prior reporting, an active plaintiff in federal and state litigation (E.D. Mo. 4:2025-cv-01316) against Black Dome and A2Z Field Services President Amie Sparks over money allegedly owed to Rulo’s own firm. Rulo is simultaneously NAMFS President and a party to litigation arising from exactly the kind of member-on-member non-payment NAMFS claims to police.

That litigation sits inside a much larger pattern this publication has tracked for years. A2Z Field Services, sold by Amie Sparks to Black Dome in November 2025 rather than completing a deal already in motion with First Rate, collapsed into months of non-payment to Field Service Technicians and Inspectors. Spectrum Solutions Acquisitions allegedly had moved to acquire Black Dome, reportedly offering unpaid Labor a below-face settlement. Foreclosurepedia’s own Firm Registry — a standing tracking system covering 47 active and historical firms across the mortgage field services industry — carries a NON-PAY flag on multiple NAMFS-member national firms simultaneously.

Then there’s the National Field Network involuntary bankruptcy: an eight-year involuntary proceeding, filed April 2018, still unresolved as of this writing, with zero distribution to Labor — not even from the estate of NFN’s own late CEO. NAMFS existed, organized, and collecting dues throughout the entire eight years that case has ground on without a single dollar reaching the Field Service Technicians and Inspectors it displaced.

This is the environment in which a trade association’s own tax filing has spent six years unable to correctly name its own president.

The Accounting Fees Nobody Will Explain

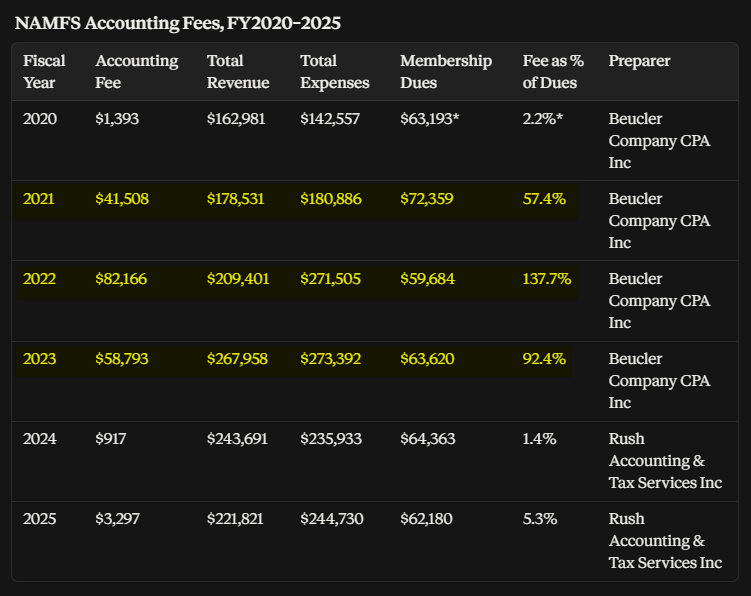
NAMFS’s Form 990 has a second problem, verified line by line against the primary filings, not estimated:

Fiscal Year Accounting Fee Membership Dues Fee as % of Dues
2020 $1,393 ~$63,193 2.2%
2021 $41,508 $72,359 57.4%
2022 $82,166 $59,684 137.7%
2023 $58,793 $63,620 92.4%
2024 $917 $64,363 1.4%
2025 $3,297 $62,180 5.3%

In FY2022, NAMFS paid its accountant more than it collected from its entire dues-paying membership that year. Across the three-year spike — FY2021 through FY2023 — NAMFS paid $182,467 to a single accounting firm, Beucler Company CPA Inc, against $195,663 in total dues collected over the same span: 93 cents of every membership dollar, gone to accounting fees alone. No Schedule O explanation. No itemized statement. No named engagement. The fee is roughly 44 to 92 times the organization’s own historical baseline, depending on which low-fee year it’s measured against. And this against the backdrop of minimal gross income increase. Many we spoke with called it a COVID slush fund.

The spike ends the exact year NAMFS switched preparers, to Rush Accounting & Tax Services Inc, for the FY2024 return — the fee falling from $58,793 to $917 in a single year, a 98.4% drop, with the switch itself as unexplained as the spike.

A Name Change, Mid-Scandal

NAMFS’s FY2025 return is the filing of record for a legal name change: the “Name change” box on Line B is checked, and the organization appears for the first time as the National Association of Asset Management & Field Services Inc — a rebrand NAMFS’s own website attributes to a 2025 board initiative for “higher ROI” and “broadening outreach.” That filing was submitted June 9, 2026, roughly three weeks past the standard deadline, well inside the extension window, but the latest-running of any year this investigation reviewed.

The rebrand lands in the same window as the Black Dome/A2Z collapse, Rulo’s own litigation as sitting NAMFS President, the tail end of the NFN bankruptcy’s eighth year, and the accounting-fee anomaly’s aftermath. Nothing in NAMFS’s own filings or public statements connects the timing of the rebrand to any of it. Whether that’s coincidence or convenience is a question this publication cannot answer from the public record — but it is a question the timing itself raises, unprompted.

A Board That, By Its Own Admission, Never Sees What It Signs Off On

Nonprofit tax-exempt status is not a formality. It is a public trust granted in exchange for a specific promise: that an organization exempt from federal income tax will conduct its affairs honestly, disclose its finances accurately, and submit to the IRS’s Form 990 precisely because the public cannot otherwise verify who is actually running the organization collecting their dues. The entire disclosure regime under IRC § 6104(d) exists because the law does not trust nonprofits to self-report only when convenient. It requires them to.

NAMFS’s own governance answers, filed on the same returns that misstate its presidency, help explain how the error survived six years without anyone catching it. Form 990’s Part VI asks every filer directly: “Has the organization provided a complete copy of this Form 990 to all members of its governing body before filing the form?” NAMFS’s answer, filed year after year: No.

NAMFS reports 15 voting board members, all designated “independent,” with a written conflict-of-interest policy and an annual disclosure requirement for officers, directors, and key employees. On paper, that is a governance structure built to catch exactly this kind of error. In practice, by the organization’s own sworn admission, the people sitting on that board — including, until 2019, Justis Smith herself — have never been shown the completed return before it goes out under Eric Miller’s signature. It is worth noting that switching from the Treasurer’s signature, who has no financial incentive, to the paid Executive Director Eric Miller who is the only paid NAMFS Board member, is sure to raise a few eyebrows. A board that never reads the document has no mechanism to notice the document is wrong. That is not a defense. It is the description of a board that has outsourced its most basic fiduciary obligation — knowing what the organization is telling the federal government about itself — to the one person signing it.

What This Is, and What It Isn’t

The relevant federal statute is 26 U.S.C. § 7206(1), which makes it a felony to willfully sign a federal return “which he does not believe to be true and correct as to every material matter.” The willfulness requirement is the entire question, and it is not one a tax filing answers on its own. There is a real difference between a genuine, repeatedly-uncaught clerical error — the same stale officer table copied forward, year after year, never flagged internally, never reviewed by a board that admits it doesn’t see the return before filing — and something else. Proving which one this is requires more than the public record provides.

This publication is not in a position to make that determination, and won’t pretend to.

What isn’t in dispute: a federal document, sworn true under penalty of perjury and filed electronically with the IRS, has misstated who ran this organization for six consecutive years, while the correct information sat on NAMFS’s own website the entire time — filed by a board that structurally never reviews what it’s signing off on, at an organization whose sitting president is embroiled in the same non-payment litigation crippling the Labor force it claims to represent, whose accounting fees briefly exceeded its entire membership base, and which changed its legal name in the same filing period as all of it. At minimum, that raises a serious question about whether NAMFS’s Executive Director, and its Board of Directors as a body, have fulfilled their fiduciary duty of care in reviewing what gets sworn true to the federal government in their name.

Foreclosurepedia is exploring formal options in response to these findings, including a Form 13909 referral to the IRS Exempt Organizations division and a complaint to the Ohio Attorney General’s Charitable Law Section, which holds oversight authority over nonprofit governance and fiduciary conduct for organizations domiciled in the state. Neither step guarantees a result — IRS complaints are confidential by law, and state charitable-oversight review is discretionary — but the underlying record, drawn entirely from NAMFS’s own federal filings and its own public statements, speaks for itself.


Sources: IRS Form 990, NAMFS/National Association of Asset Management & Field Services Inc, FY2016–FY2025 (ProPublica Nonprofit Explorer, EIN 34-1800707); Internet Archive Wayback Machine captures of namfs.org/about, July 2019–March 2025; NAMFS October 2022 newsletter; namfs.org current leadership page; prior Foreclosurepedia reporting on the Black Dome/A2Z collapse, the NFN bankruptcy, and Foreclosurepedia’s Firm Registry NON-PAY designations.

Signature Block History: NAMFS Form 990, FY2016–FY2025

Fiscal Year Signed By Title Date Signed President Listed Actual President (per NAMFS’s own site) Accurate?
2016 Paul W. Magaha Treasurer 11-13-17 Adam Miles Adam Miles ✅ Accurate
2017 Paul W. Magaha Treasurer 11-1-18 Justis Smith Justis Smith ✅ Accurate
2018 Paul W. Magaha Treasurer 11-13-19 Justis Smith Justis Smith ✅ Accurate
2019 Eric Miller Executive Director 2020-06-02 Justis Smith Smith (partial) / Zoldowski (partial) ⚠️ Transition year
2020 Eric Miller Executive Director 2021-05-11 Justis Smith Matt Zoldowski ❌ False
2021 Eric Miller Executive Director 2022-04-26 Justis Smith Matt Zoldowski ❌ False
2022 Eric Miller Executive Director 2023-05-02 Justis Smith Matt Zoldowski ❌ False
2023 Eric Miller Executive Director 2024-05-14 Justis Smith Matt Zoldowski ❌ False
2024 Eric Miller Executive Director 2025-05-14 Justis Smith Zoldowski → Rulo ❌ False
2025 Eric Miller Executive Director 2026-05-19 Justis Smith Chad Rulo ❌ False

What the table shows at a glance: every year Magaha signed, the perjury declaration matched reality. The switch to Miller’s signature is the exact point the declaration stops matching reality — and stays wrong for six consecutive years afterward, never once corrected.

Under Penalty of Perjury: NAMFS’s Federal Filings Say Justis Smith Runs an Organization She Hasn’t Led in Six Years

A trade association whose own sitting president is embroiled in the same non-payment litigation crippling the Labor force it claims to represent. A three-year accounting-fee spike that briefly exceeded the entire membership’s dues. A legal name change filed mid-scandal. A board that, by its own admission, never sees the document before it goes to the IRS. And at the center of all of it, a federal tax filing — signed under penalty of perjury, transmitted electronically — that has named the wrong president for six straight years.

Every Form 990 carries the same declaration above the signature line: “Under penalties of perjury, I declare that I have examined this return, including accompanying schedules and statements, and to the best of my knowledge and belief, it is true, correct, and complete.” That declaration has been signed, year after year, on a document transmitted electronically to the IRS — confirmed directly by the “efile” designation ProPublica’s Nonprofit Explorer attaches to each filing, not an assumption.

For years, it was signed correctly. Then it wasn’t.

The President Who Isn’t

Treasurer Paul Magaha signed NAMFS’s returns through at least FY2018, and while he did, the officer table tracked reality. The FY2016 return correctly lists Adam Miles as President. The FY2017 and FY2018 returns correctly list Justis Smith as President, following her actual succession to the role.

Then, starting with the FY2019 return — the first signed not by Magaha but by Executive Director Eric Miller — the roster stopped moving. Every filing since, through FY2025, lists Justis Smith as President, 8 hours a week, $0 compensation. Six consecutive years, under one man’s signature, while the actual presidency changed hands twice.

Signature Block History: NAMFS Form 990, FY2016–FY2025

Fiscal Year Signed By Title Date Signed President Listed Actual President (per NAMFS’s own site) Accurate?
2016 Paul W. Magaha Treasurer 11-13-17 Adam Miles Adam Miles ✅ Accurate
2017 Paul W. Magaha Treasurer 11-1-18 Justis Smith Justis Smith ✅ Accurate
2018 Paul W. Magaha Treasurer 11-13-19 Justis Smith Justis Smith ✅ Accurate
2019 Eric Miller Executive Director 2020-06-02 Justis Smith Smith (partial) / Zoldowski (partial) ⚠️ Transition year
2020 Eric Miller Executive Director 2021-05-11 Justis Smith Matt Zoldowski ❌ False
2021 Eric Miller Executive Director 2022-04-26 Justis Smith Matt Zoldowski ❌ False
2022 Eric Miller Executive Director 2023-05-02 Justis Smith Matt Zoldowski ❌ False
2023 Eric Miller Executive Director 2024-05-14 Justis Smith Matt Zoldowski ❌ False
2024 Eric Miller Executive Director 2025-05-14 Justis Smith Zoldowski → Rulo ❌ False
2025 Eric Miller Executive Director 2026-05-19 Justis Smith Chad Rulo ❌ False

Every year Magaha signed, the perjury declaration matched reality. The switch to Miller’s signature is the exact point the declaration stops matching reality — and stays wrong for six consecutive years afterward, never once corrected.

Archived snapshots of namfs.org’s own leadership page, captured independently by the Internet Archive’s Wayback Machine, confirm the actual sequence:

  • July 21, 2019: Justis Smith, President, 2017–2019.
  • September 20, 2019: Matt Zoldowski, President, 2019–2021.
  • April 1, 2023: Matt Zoldowski, President, 2022–2024.
  • March 23, 2025: Chad Rulo, President, 2024–2026.

NAMFS’s own October 2022 newsletter corroborates the middle of that timeline directly: “The Officers for the 2022-24 term are: Matt Zoldowski – President.” This publication’s own reporting called Zoldowski “NAMFS President” in October 2023, and called Rulo “the latest NAMFS President” by April 2025 — independent, real-time confirmation the website’s timeline was accurate the whole time.

Treating FY2019 as the genuine transition year, six tax years — FY2020 through FY2025, all signed by Miller — are unambiguously wrong. At the 8 hours a week the return itself claims: 8 × 52 × 6 = 2,496 hours of board service attributed to a woman who left the role in 2019, on a federal document sworn true under penalty of perjury, signed by the same man, every single year, without correction.

Meanwhile, the Real President Is in Court

The man NAMFS’s own website says actually holds the presidency is not a bystander to this industry’s worst pattern. Chad Rulo is CEO of First Rate Field Services — and, per this publication’s own prior reporting, an active plaintiff in federal and state litigation (E.D. Mo. 4:2025-cv-01316) against Black Dome and A2Z Field Services President Amie Sparks over money owed to Rulo’s own firm. Rulo is simultaneously NAMFS President and a party to litigation arising from exactly the kind of member-on-member non-payment NAMFS claims to police.

That litigation sits inside a much larger pattern this publication has tracked for years. A2Z Field Services, sold by Amie Sparks to Black Dome in November 2025 rather than completing a deal already in motion with First Rate, collapsed into months of non-payment to Field Service Technicians and Inspectors. Spectrum Solutions Acquisitions has since moved to acquire Black Dome, reportedly offering unpaid Labor a below-face settlement. Foreclosurepedia’s own Firm Registry — a standing tracking system covering 47 active and historical firms across the mortgage field services industry — carries a NON-PAY flag on multiple NAMFS-member national firms simultaneously.

Then there’s the National Field Network bankruptcy: an eight-year involuntary proceeding, filed April 2018, still unresolved as of this writing, with zero distribution to Labor — not even from the estate of NFN’s own late CEO. NAMFS existed, organized, and collecting dues throughout the entire eight years that case has ground on without a single dollar reaching the Field Service Technicians and Inspectors it displaced.

This is the environment in which a trade association’s own tax filing has spent six years unable to correctly name its own president.

The Accounting Fees Nobody Will Explain

NAMFS’s Form 990 has a second problem, verified line by line against the primary filings, not estimated:

Fiscal Year Accounting Fee Membership Dues Fee as % of Dues
2020 $1,393 ~$63,193 2.2%
2021 $41,508 $72,359 57.4%
2022 $82,166 $59,684 137.7%
2023 $58,793 $63,620 92.4%
2024 $917 $64,363 1.4%
2025 $3,297 $62,180 5.3%

In FY2022, NAMFS paid its accountant more than it collected from its entire dues-paying membership that year. Across the three-year spike — FY2021 through FY2023 — NAMFS paid $182,467 to a single accounting firm, Beucler Company CPA Inc, against $195,663 in total dues collected over the same span: 93 cents of every membership dollar, gone to accounting fees alone. No Schedule O explanation. No itemized statement. No named engagement. The fee is roughly 44 to 92 times the organization’s own historical baseline, depending on which low-fee year it’s measured against.

The spike ends the exact year NAMFS switched preparers, to Rush Accounting & Tax Services Inc, for the FY2024 return — the fee falling from $58,793 to $917 in a single year, a 98.4% drop, with the switch itself as unexplained as the spike.

A Name Change, Mid-Scandal

NAMFS’s FY2025 return is the filing of record for a legal name change: the “Name change” box on Line B is checked, and the organization appears for the first time as the National Association of Asset Management & Field Services Inc — a rebrand NAMFS’s own website attributes to a 2025 board initiative for “higher ROI” and “broadening outreach.” That filing was submitted June 9, 2026, roughly three weeks past the standard deadline, well inside the extension window, but the latest-running of any year this investigation reviewed.

The rebrand lands in the same window as the Black Dome/A2Z collapse, Rulo’s own litigation as sitting NAMFS President, the tail end of the NFN bankruptcy’s eighth year, and the accounting-fee anomaly’s aftermath. Nothing in NAMFS’s own filings or public statements connects the timing of the rebrand to any of it. Whether that’s coincidence or convenience is a question this publication cannot answer from the public record — but it is a question the timing itself raises, unprompted.

A Board That, By Its Own Admission, Never Sees What It Signs Off On

Nonprofit tax-exempt status is not a formality. It is a public trust granted in exchange for a specific promise: that an organization exempt from federal income tax will conduct its affairs honestly, disclose its finances accurately, and submit to the IRS’s Form 990 precisely because the public cannot otherwise verify who is actually running the organization collecting their dues. The entire disclosure regime under IRC § 6104(d) exists because the law does not trust nonprofits to self-report only when convenient. It requires them to.

NAMFS’s own governance answers, filed on the same returns that misstate its presidency, help explain how the error survived six years without anyone catching it. Form 990’s Part VI asks every filer directly: “Has the organization provided a complete copy of this Form 990 to all members of its governing body before filing the form?” NAMFS’s answer, filed year after year: No.

NAMFS reports 15 voting board members, all designated “independent,” with a written conflict-of-interest policy and an annual disclosure requirement for officers, directors, and key employees. On paper, that is a governance structure built to catch exactly this kind of error. In practice, by the organization’s own sworn admission, the people sitting on that board — including, until 2019, Justis Smith herself — have never been shown the completed return before it goes out under Eric Miller’s signature. A board that never reads the document has no mechanism to notice the document is wrong. That is not a defense. It is the description of a board that has outsourced its most basic fiduciary obligation — knowing what the organization is telling the federal government about itself — to the one person signing it.

What This Is, and What It Isn’t

The relevant federal statute is 26 U.S.C. § 7206(1), which makes it a felony to willfully sign a federal return “which he does not believe to be true and correct as to every material matter.” The willfulness requirement is the entire question, and it is not one a tax filing answers on its own. There is a real difference between a genuine, repeatedly-uncaught clerical error — the same stale officer table copied forward, year after year, never flagged internally, never reviewed by a board that admits it doesn’t see the return before filing — and something else. Proving which one this is requires more than the public record provides.

This publication is not in a position to make that determination, and won’t pretend to.

What isn’t in dispute: a federal document, sworn true under penalty of perjury and filed electronically with the IRS, has misstated who ran this organization for six consecutive years, while the correct information sat on NAMFS’s own website the entire time — filed by a board that structurally never reviews what it’s signing off on, at an organization whose sitting president is embroiled in the same non-payment litigation crippling the Labor force it claims to represent, whose accounting fees briefly exceeded its entire membership base, and which changed its legal name in the same filing period as all of it. At minimum, that raises a serious question about whether NAMFS’s Executive Director, and its Board of Directors as a body, have fulfilled their fiduciary duty of care in reviewing what gets sworn true to the federal government in their name.

Foreclosurepedia is exploring formal options in response to these findings, including a Form 13909 referral to the IRS Exempt Organizations division and a complaint to the Ohio Attorney General’s Charitable Law Section, which holds oversight authority over nonprofit governance and fiduciary conduct for organizations domiciled in the state. Neither step guarantees a result — IRS complaints are confidential by law, and state charitable-oversight review is discretionary — but the underlying record, drawn entirely from NAMFS’s own federal filings and its own public statements, speaks for itself.

Here are the NAMFS IRS tax filings spoken about today:

FY2019: https://projects.propublica.org/nonprofits/organizations/341800707/202031979349304828/full
FY2020: https://projects.propublica.org/nonprofits/organizations/341800707/202101459349301020/full
FY2021: https://projects.propublica.org/nonprofits/organizations/341800707/202211389349300131/full
FY2022: https://projects.propublica.org/nonprofits/organizations/341800707/202311369349300516/full
FY2023: https://projects.propublica.org/nonprofits/organizations/341800707/202421729349301112/full
FY2024: https://projects.propublica.org/nonprofits/organizations/341800707/202501509349300015/full
FY2025: https://projects.propublica.org/nonprofits/organizations/341800707/202601609349300905/full


Editor’s Note: We changed the title for clarity and length. We will continue updating this article as information becomes available and via other articles and podcasts.

The Obscene Math: Eric Miller Takes $110,000 While Inspections Still Pay $8

IAFST NAMFS

Diesel just hit $6.51 a gallon. Mortgages are pushing 7%. Tariffs are stacking onto every part, every truck, every tool a Field Service Technician needs to do the job. NAMFS’s Executive Director hasn’t felt any of it — and the paper trail behind his salary raises more questions than it answers.

AAA’s national average for diesel hit $6.51 a gallon today, September 20 — up from $3.71 a year ago, an increase of more than 75% in twelve months. A Field Service Technician running a 30-gallon tank now pays roughly $195 to fuel up. At $8 an inspection — the standard rate, unchanged for years — that single fill-up costs nearly 24 completed inspections before a dime goes toward rent, insurance, or food.

The 30-year fixed mortgage sits at 6.95%, per Freddie Mac, up from 6.26% a year ago. Every distressed property that rate pushes into foreclosure becomes another job on a Field Service Technician’s route. It does not become another dollar in their pocket. Tariffs on imported vehicle parts, equipment, and materials have layered on top of that, raising the cost of the truck, the mower, and the tools the job requires — while the rate paid for the job itself hasn’t moved.

Inflation ran 3.4% for the twelve months ending in August, per the Bureau of Labor Statistics, with energy up 16.3% and food up 2.7%. Grass cuts still pay $25 to $30. Winterizations still pay $45 to $50 — confirmed on a current ServiceLink rate sheet. Inspections still pay $7 to $9. None of it has moved. Everything around it has.

Eric Miller has not had that problem.

Four years unpaid, then the money started

Miller first appears in NAMFS’s own filings in 2007 — as unpaid Vice President, 3 hours a week, while Tim Doehner became the organization’s first-ever paid Executive Director at $36,000. Miller became unpaid President in 2009, still drawing $0, still logging hours on the side of whatever his actual job was. He held that unpaid post through 2010. Four years of volunteer board service before he ever saw a NAMFS paycheck.

In 2011, that changed. Miller became Executive Director at $100,625. It did not stay there.

Fiscal Year Eric Miller’s Compensation
2011 (first year as ED) $100,625
2012 $112,044
2013–2017 $120,215 flat
2018 $119,789
2019 $138,107 — his highest figure on record
2020–2023 $110,000 flat
2024 $114,231
2025 $110,000

The membership funding it has been shrinking the entire time

Fiscal Year Membership Dues Miller’s Comp Comp as % of Dues
2013 $192,210 $120,215 62.5%
2017 $129,375 $120,215 92.9%
2018 $120,141 $119,789 99.7%
2021 $72,359 $110,000 152.0%
2022 $59,684 $110,000 184.3%
2023 $63,620 $110,000 172.9%
2024 $64,363 $114,231 177.5%
2025 $62,180 $110,000 176.9%

Dues peaked in 2013 at $192,210. By 2025 they’d fallen to $62,180 — a two-thirds collapse. Miller’s pay didn’t follow it down. By 2018 his salary equaled essentially the entire dues base. Every year since 2021, it has exceeded it outright — meaning NAMFS now runs a structural deficit against its own core membership revenue every single year, just to keep one man paid six figures.

Put it in Labor’s terms: at $8 an inspection, Miller’s 2025 salary alone equals 13,750 completed inspections. That is more inspections than most individual Field Service Technicians and Inspectors will complete in a working lifetime — drawn by one man, at a desk, while dues shrink and diesel sets records.

The organization’s overall finances tell the same story from a different angle. Net assets sat at $271,263 in 2011, Miller’s first year as ED. By 2025 they had fallen to $62,540 — a decline of more than 75% over the same stretch his personal compensation was holding flat or climbing.

The filings don’t inspire confidence

NAMFS’s FY2024 return reports $114,231 in aggregate compensation to its officers and key employees — a figure this piece uses, since Miller is the organization’s only employee and the only plausible recipient. But that same return’s individual compensation table, Part VII, lists Miller’s personal line at $0. NAMFS’s own document does not agree with itself about whether its Executive Director was paid $114,231 that year or nothing at all. The organization has one employee. It should not be possible to get that wrong — then again the NAMFS CPA seemed to have been getting high on the COVID slush fund, err pricing. We do not know as NAMFS continues to refuse to provide their IRS 990, required by federal law, or reply to any questions submitted.

NAMFS’s FY2009 filing shows a nearly identical pattern under Doehner: his individual line reads $0 against $67,984 paid out in aggregate that year. Whatever else has changed at NAMFS over fifteen years, sloppy or evasive bookkeeping around executive pay apparently hasn’t.

Then there’s the accounting bill, and this one deserves its own accounting

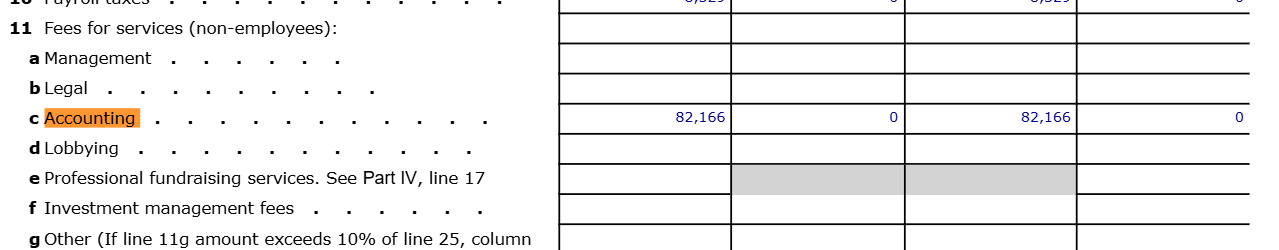
For over a decade, NAMFS paid its accountant between $875 and $6,223 a year — the kind of number you’d expect from a trade association with one employee and a PO box for an address. Then, starting with FY2021, that number exploded: $41,508. The next year, FY2022, it nearly doubled again to $82,166 — confirmed directly off Part IX, line 11c of the primary filing, signed by Eric Miller himself on May 2, 2023. FY2023 came in at $58,793.

NAMFS FY2000 FY2025 Accounting Fees

Put that $82,166 next to what NAMFS actually took in that year. Total revenue for FY2022 was $209,401. The accounting fee alone consumed 39% of it. Total expenses were $271,505 — meaning accounting fees ate nearly a third of everything the organization spent, in a year it ran a $62,104 deficit.

Zoom out further. Across the three-year spike — FY2021 through FY2023 — NAMFS paid its accountant a combined $182,467. Across those same three years, total membership dues collected came to $195,663. Over that stretch, this trade association spent almost every dollar its own membership paid in dues on accounting fees alone — thirteen times its own historical high-water mark of $6,223, on an organization whose entire operation fits on a single Form 990-EZ in leaner years.

No Schedule O explanation. No itemized statement. No named engagement, no audit, no forensic review, no restatement — just a line item, three years running, from the same preparer (Beucler Company CPA Inc, Tiffin, OH), for an association with one employee and a PO box in Stow, Ohio. The fee dropped to $917 the moment NAMFS switched accountants for FY2024. Whatever justified tens of thousands of dollars a year in accounting work at Beucler apparently stopped being necessary the day Beucler stopped doing the accounting.

There is no version of a small 501(c)(6) trade association — one employee, sub-$300K in annual revenue, a membership that could fit in a hotel conference room — where a legitimate accounting engagement runs $82,166 in a single year. Either NAMFS was paying for something far beyond ordinary bookkeeping and compilation work, or the money went somewhere the filing doesn’t account for. NAMFS’s own return doesn’t say which, and nobody at the organization has explained it.

Accounting Fees NAMFS

Who’s actually running this thing is also an open question

None of this is new to the NAMFS Regime. It’s the same pattern #OpNAMFS has tracked for over a decade: a shrinking, aging membership propping up an Executive Director salary the industry can no longer justify, inconsistent paperwork nobody at NAMFS seems in a hurry to fix, and a leadership roster that doesn’t match its own public-facing website — all while the Field Service Technicians and Inspectors funding it eat diesel prices, mortgage rates, and tariff-driven equipment costs on a pay scale that hasn’t moved in years.


For the record: this publication spent years unable to confirm NAMFS’s actual tax status. NAMFS refused, repeatedly, to produce its Form 990 on direct request — despite IRC § 6104(d) requiring any 501(c) organization to make its return available to the public on demand. That stonewalling is the reason earlier Foreclosurepedia coverage treated NAMFS’s nonprofit status as an open question rather than a settled fact. Primary IRS e-file data, pulled directly rather than through NAMFS, now confirms the organization has held 501(c)(6) tax-exempt status throughout. The finding here isn’t that NAMFS lied about being a nonprofit — it’s that they hid the paperwork proving it, for years, from the Labor force paying their Executive Director’s salary at the pump.

Diesel at Historic Highs, Inflation Out of Control, and a War Half a World Away: How Labor Is Being Crushed While Our Industry Refuses to Raise Pricing

IAFST HUD HQ

Foreclosurepedia has documented the squeeze on Field Service Technicians and Inspectors for years. What is happening now is not a squeeze. It is a vice, and it is being turned by forces entirely outside the control of the people who actually do the work.

Diesel hit a national average of $6.50 a gallon, up from $3.70 a year ago. That is a 76 percent increase in twelve months. Regular gasoline sits at $4.47. Mid-grade at $4.96. Premium at $5.35. Field Service Technicians and Inspectors cannot defer fuel to reach a door an Order Mill ordered them to knock on. Every mile driven to a property, every trip to a hardware store for a lock change, every run to a UPS drop for a report that was due yesterday, all of it runs on diesel that now costs nearly twice what it did a year ago. Labor absorbs that difference out of pocket because the Order Mills have not adjusted a single fee schedule to account for it.

Inflation is not cooling. It is compounding. The cost of everything a Field Service Technician or Inspector needs to do the job: fuel, vehicles, tires, tools, locks, boards, tarps, PPE, insurance, licensing fees, software subscriptions, has climbed steadily for three years, and in some categories has doubled. Wages and fee schedules in this industry have not moved in over thirty years. That is not an exaggeration. The pricing structure that NAMFS Order Mills use today is materially the same structure they used in the early 1990s. A grass cut that paid $35 in 1994 pays $35 in 2026. A property inspection that paid $12 in 1994 pays $12 in 2026. The dollar has lost more than half its purchasing power since then. Labor has been asked to do more work, drive farther, carry more liability, and absorb more cost, for the same nominal fee, for three decades.

Now add a war. The conflict with Iran has rattled global energy markets, pushed crude higher, and sent diesel, already tight from refinery constraints and seasonal demand, into territory that makes the last record look like a waypoint rather than a peak. When diesel goes up, everything goes up. Freight costs rise. Goods cost more. Services cost more. The one thing that does not rise is what Order Mills pay Labor. The cost of the war is being passed down the chain until it lands on the independent contractor with a truck, a phone, and a route sheet.

Borrowing costs are climbing alongside it. The 30-year fixed mortgage is running between 7.04 and 7.20 percent APR. The 10-year Treasury yield touched 5.04 percent earlier this week, marking some of its highest levels since 2007, nearly two decades ago. For Labor carrying debt to cover fuel and equipment while waiting on Order Mills to pay, every one of those numbers compounds the hole. Higher rates mean fewer refinances, fewer originations, fewer loss mitigation workouts, and more foreclosures, which means more work dumped on the same Labor pool at the same thirty-year-old fee schedule.

Tariffs have crippled buying power on top of all of it. Imported goods cost more. Domestic goods cost more because their inputs cost more. Tools, parts, vehicles, tires, electronics, everything a Field Service Technician touches has a tariff-affected component in its supply chain. The dollar in Labor’s pocket buys less than it did last quarter, let alone last year, let alone 1994.

NAMFS Order Mills, the same firms Foreclosurepedia has catalogued and flagged in its Firm Registry, continue to treat Labor as an inexhaustible, disposable input. They cut pricing when volumes drop. They cut pricing when volumes rise, claiming scale. They cut pricing when a competitor underbids, then demand the same scope at the lower number. They pay late, pay short, or do not pay at all, and when Labor asks why, the answer is that the client has not paid them. As Foreclosurepedia has documented repeatedly, that answer is often not true.

The result is what you see across the industry right now: experienced Field Service Technicians and Inspectors leaving in numbers the Order Mills cannot replace. The ones who stay are running older trucks, deferring maintenance, skipping insurance, and working longer hours to make the same real income they made a decade ago. The ones who leave are not coming back. The Order Mills have no pipeline for replacements because no rational person enters this industry at $8 an inspection when diesel is $6.50 a gallon.

This is not a market correction. It is a structural failure, and it has been building for thirty years. Diesel at record highs, inflation compounding, a war driving energy costs, tariffs eroding buying power, mortgages above 7 percent, any one of these would be enough to strain Labor. Together, they are breaking it. And the industry’s response has been to keep paying 20th Century prices for 2026 work.

Foreclosurepedia will continue to document which firms are doing this, which ones are paying late, which ones are not paying at all, and which ones are hiding behind client non-payment excuses that do not hold up. The Firm Registry is public. The spreadsheets are public. Labor deserves to know who it is working for before it takes the assignment.


If you are a Field Service Technician or Inspector and you have documentation of non-payment, fee cuts, or scope creep without compensation, Foreclosurepedia wants to hear from you.

HUD Puts a Nationwide Multifamily Construction Inspection Contract on the Street — Here’s What Firms Need to Know

The U.S. Department of Housing and Urban Development’s Office of Multifamily Housing has put out a solicitation that ought to have the attention of every inspection firm, every Field Service Technician and Inspector, and every construction consultant working the government contracting space. HUD is looking to lock down onsite inspection support for new construction and substantial rehabilitation projects tied to its multifamily mortgage insurance underwriting and capital advance programs — and the Agency isn’t playing small. This is a nationwide, multi-year vehicle, and it’s structured to bring on multiple contractors across five separate regions of the country.

What HUD Is Buying

The scope is straightforward on its face and demanding in practice: contractors will conduct onsite inspections of multifamily housing projects under construction or undergoing substantial rehabilitation, feeding HUD the field and site data the Agency needs to make underwriting and construction-phase decisions on its mortgage insurance and capital advance programs. This is inspection work in the truest sense — boots on the ground, documenting the physical condition and progress of a project so the government can make an informed call on federally backed financing.

Structure and Dollars

HUD intends to award this as a Firm-Fixed-Price, Multiple-Award Indefinite Delivery/Indefinite Quantity contract, set aside entirely for small business concerns. No large business need apply, and no set-aside status means no seat at the table. The Agency anticipates making up to three awards in each of five geographic regions — Northeast, Southeast, Midwest, Southwest, and West — covering every state plus Washington, D.C. and Puerto Rico. A firm is not required to bid every region, but HUD has made clear it will reject any regional proposal that only partially covers the territory it claims.

The dollar figures are real. The master IDIQ carries a guaranteed minimum of $133,000 against a ceiling of $37 million. Broken down by region, the guaranteed minimums run from $10,000 in the Midwest up to $45,000 in the Southwest, with regional ceilings ranging from roughly $2.35 million in the Midwest to nearly $11.82 million in the Southwest. The base period of performance runs a full five years, February 1, 2027 through January 31, 2032, with an option to extend services up to six additional months.

HUD has also written in on-ramp and off-ramp provisions, meaning the pool of awarded contractors isn’t necessarily frozen for five years. The Agency can bring additional small businesses onto the vehicle later if it decides more capacity or competition is warranted, and it can push a non-performing contractor out of the active ordering rotation. Firms that get in on this now should read that as an argument for staying sharp on performance, not a reason to slow-walk the proposal.

Why This Matters to the Field

Foreclosurepedia has spent years documenting how the mortgage field services industry treats the people who actually do the work — the Field Service Technicians and Inspectors who show up at the property, take the photos, and file the reports that servicers, investors, and now HUD itself rely on to make decisions worth billions of dollars. A contract of this size, spread across every region of the country, is the kind of opportunity that can either get built on fair subcontracting terms or get run the same way too much of this industry already runs: primes taking the fixed-price award and squeezing the field on the back end. Small businesses winning a seat on this IDIQ have a rare chance to set the terms of engagement with their own Inspectors from day one, rather than inheriting a race-to-the-bottom pay structure from someone else’s contract.

The Clock Is Running

This is a real federal procurement, not a placeholder notice, and it carries real deadlines. Firms considering a bid need to move now on capability statements, teaming decisions, and pricing methodology — HUD’s pricing requirements call for a detailed mathematical breakdown of labor categories, rates, and hours behind every unit price, not a back-of-the-envelope number. That takes time to build correctly, and it is not something to start the week a proposal is due.

Foreclosurepedia isn’t publishing the direct solicitation link here. If your firm is small-business certified, has genuine multifamily construction inspection capability, and wants more detail on this opportunity — including which regions still make sense for a competitive bid and what the technical and pricing proposal actually needs to contain — reach out to Foreclosurepedia directly. We’ve covered this industry from the field up for years, and we’d rather see this contract go to firms that will treat their Field Service Technicians and Inspectors right than watch it disappear into the same consolidation pattern we’ve spent this publication’s history writing about.